Bond Market Turmoil Hits Developing Countries Economies Worldwide
Global policymakers are grappling with the aftermath of bond market turmoil that has left its mark on economies worldwide.
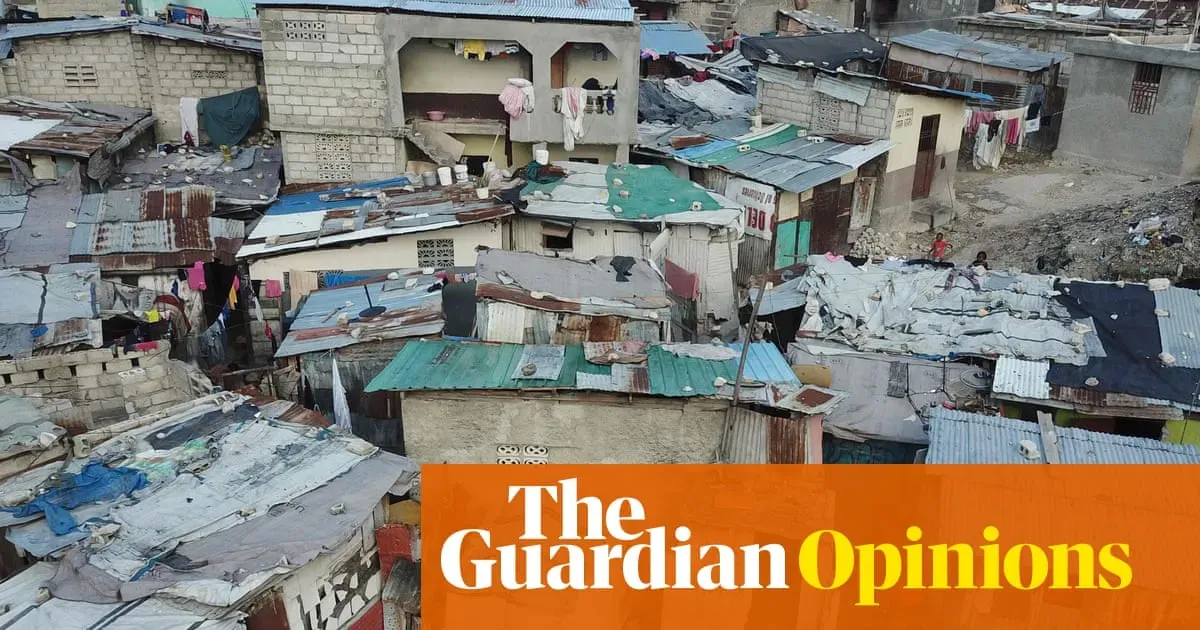
Global policymakers are grappling with the aftermath of bond market turmoil that has left its mark on economies worldwide. The chaos is particularly acute in developing countries, where debt servicing costs have become a significant burden.
These nations face a triple whammy: rising borrowing costs, dwindling government revenues, and increasing pressure to allocate scarce resources towards essential public services. The situation is further complicated by the pressing need for investments that can help them adapt to climate change.
Markets have been volatile in recent weeks, with investors dumping government bonds in response to global events such as the war in the Middle East and the spending habits of the US White House. This has driven up borrowing costs across the board, putting developing countries at a particular disadvantage.
Finance ministers and central bankers from around the world are gathering in Bangkok this week for annual meetings with the International Monetary Fund and the World Bank. While they may be reluctant to directly criticize the Trump administration's policies, they are all aware of the impact its actions have had on global markets.
Experts have warned that debt servicing costs already account for a significant portion of government revenues in developing countries, leaving little room for investment in essential services or climate resilience initiatives. The situation is particularly dire in low-income nations where these costs can reach as high as 70% of government revenues.
The global economic forum known as the G20 has been a key platform for discussing international debt issues in recent years.
Under its chairmanship, previous efforts to address debt have included establishing the IMF-administered Common Framework, which allows struggling countries to apply for assistance, and suspending repayments for borrowers affected by the Covid crisis.
However, this year's chair, the US under President Trump, has focused on other aspects of the G20's remit, such as promoting global economic growth. This shift in priorities is ironic, given that the ongoing conflict with Iran is a major obstacle to achieving economic growth.
The UK will take over the G20 presidency next year, and Labour has indicated it will have different priorities for its term in office. The party plans to seek a global agreement on regulating artificial intelligence, a goal that may seem ambitious but is worth pursuing nonetheless.
Labour's foreign secretary, Ed Miliband, stated at his party's conference last month that the UK would use its G20 presidency to address unsustainable debt and mobilize international cooperation. This commitment builds on the progress made by Labour's previous government in addressing debt and development issues.
The landscape of international development has undergone significant changes since the Make Poverty History movement secured substantial debt relief for over 30 countries in 2005.
Key differences have been highlighted by Kirsty McNeill, current development minister and a veteran of that campaign. She noted that the UK is now dealing with private creditors rather than public ones, which shifts the dynamics of debt management.
The situation has become more complex due to changing global economic conditions. The lines between rich and poor countries are no longer as clearly defined, making it harder to identify those in need of support. This shift has blurred the distinction between protagonists and antagonists in development efforts.
Despite these challenges, ministers have signaled their willingness to engage with proposals aimed at addressing debt burdens. One such plan, drawn up by Development Finance International (DFI), would grant 27 heavily indebted countries a 10-year respite from debt service costs below 10% of their revenues.
The plan to provide relief to developing nations would involve private creditors absorbing a significant portion of the costs. This could be achieved through a combination of reduced interest rates and extended loan terms, rather than outright debt forgiveness.
Six small island developing states that do not meet the debt burden threshold but are frequently affected by natural disasters could also receive temporary reprieve under this initiative. These countries would be granted a five-year "holiday" from debt repayment following their next major weather-related disaster, at an estimated annual cost of $700m.
The scope of the plan could be expanded to include another five countries, including Pakistan and Angola. This would provide additional relief to nations struggling with debt obligations and seeking to allocate resources towards climate and development goals.
International financial institutions such as the IMF and World Bank would bear relatively low costs under this plan, as they typically only intervene after other creditors have exhausted their options.
The groundwork is being laid for a G20 agenda that tackles the root causes of global economic instability. This shift in focus comes as developing nations are bearing the brunt of bond market turmoil.
A new approach could be a major departure from past policies, particularly those initiated by Keir Starmer's Labour government when it cut aid spending to fund defence initiatives.
Facts based on reporting originally published by The Guardian Business.
You may republish this story, in full or in part, if you credit Noti Group and link to it (licence CC BY 4.0). Photos are not included.